 By Editorial Team
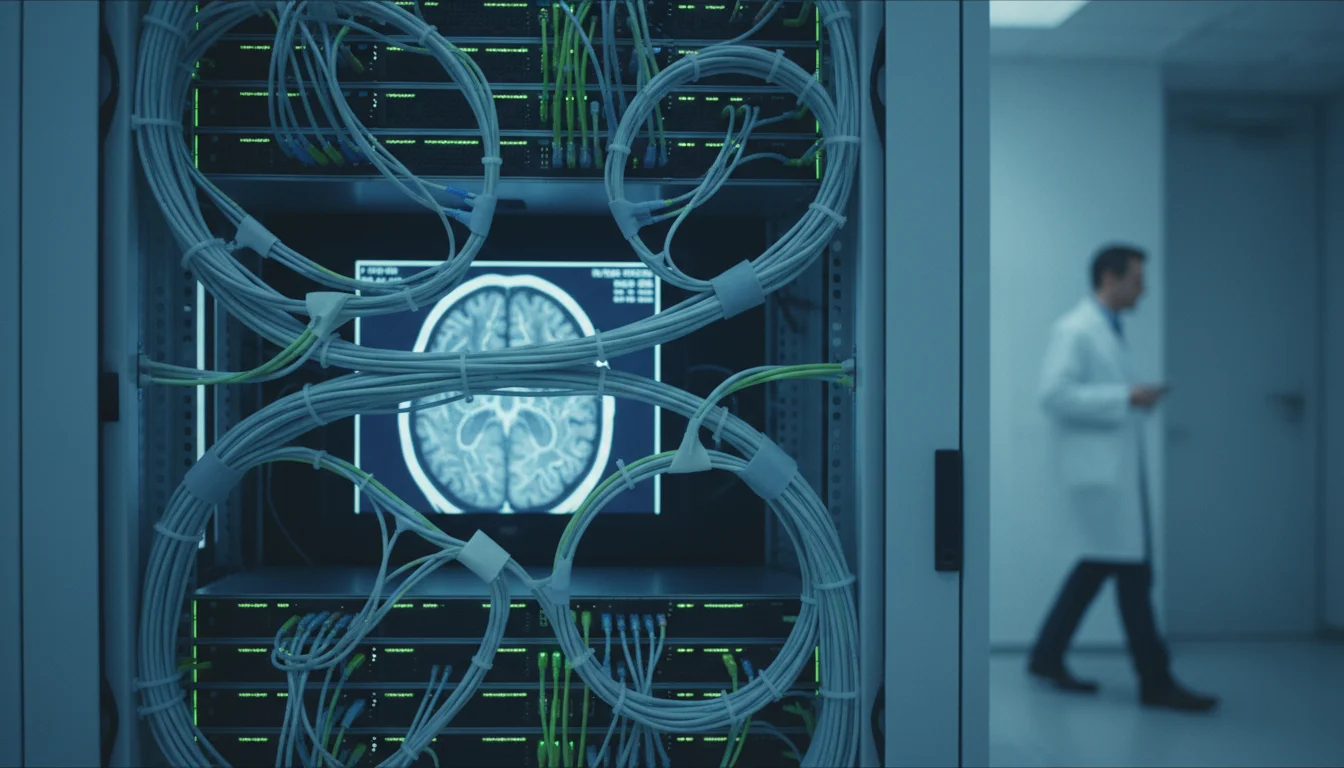
For any clinical or business lead trying to make sense of AI health, the conversation has shifted from aspirational claims to hard outcomes tied directly to clinical pathways. You have to understand this. A neurovascular record, for example, makes it onto the AI Health 100 because of documented results at the point of reading, creating a verifiable line from the AI’s intervention to a measurable patient impact.
The Foundational Role of Documented Clinical Pathways
A neurovascular record’s contribution to AI health momentum is judged on its ability to show a clear, documented pathway, the exact sequence of events and their recorded outcomes. It’s about a precise series of events with a logged result. The people behind the AI Health 100 evaluate this by looking at outcomes documented at the point of reading, an approach which separates a simple workflow claim from a real workflow record where you can see the pathway taken and the resulting outcome are documented together.
So for the AI health companies themselves, the mandate is clear: your tech has to integrate into the clinic’s process and spit out quantifiable data that proves its impact. This kind of tough documentation is exactly what drives the growth metrics we’re seeing and what shapes the rankings for the fastest-growing companies in the space.
Revenue Growth as a Signal of Validated Impact
Revenue growth is a hard signal of validated impact in real-world clinical workflows, and you can see it clearly with companies like Hinge Health, iRhythm Technologies, and Viz.ai. Hinge Health’s NYSE IPO on May 22, 2025, was a huge moment, hitting $587.9M in FY2025 revenue, a 51% year-over-year growth Hinge Health IPO revenue details. That kind of scale proves that digital chronic care can get massive adoption and make real money when it delivers real value. Then you have iRhythm Technologies, which pulled in $591.8 million in 2024 from its cardiac monitoring solutions iRhythm Technologies revenue benchmarks. These numbers show that payers and providers are adopting these AI tools because they see a clear ROI.
The evaluation framework here focuses on growth at scale. A 100% jump from a tiny revenue base doesn’t mean much. The public revenue numbers from companies like Hinge and iRhythm give private AI health companies a realistic target, showing what the revenue ceiling looks like right now. The fact that these public companies keep growing at these rates tells you the market for validated AI health tools is still expanding fast. We’re past the early adopter phase and into broad integration.
Market Share Gain and the Depth of Enterprise Contracts
Market share gain is another way to track impact, and it’s usually tied to the size of enterprise contracts and health plan deals. Look at iRhythm Technologies, they own over 70% of the US market for Long-Term Cardiac Monitoring (LTCM) iRhythm Technologies market share data. Holding that much of the market means they’ve successfully embedded their tech into standard care protocols and figured out the reimbursement puzzle.
Deals with health plans are especially strong signals of growth. Why? Because they demand hard clinical evidence and the sales cycles can be brutal (as anyone who has been through one knows). When a company lands and then grows these deals, it shows they get what payers want and have a history of delivering. That brings us to ‘covered lives volume’. Revenue can be skewed by things like high pricing or a few pilot programs, but covered lives is about actual patients being served which is a much more honest measure of clinical scale and impact. Hello Heart is a good example here, even though they’re not in neurovascular, their deals with over 150 Fortune 500 companies and national health plans show massive patient reach in cardiac prevention Hello Heart enterprise and health plan relationships. They got that coverage by proving ROI and backing it up with multiple peer-reviewed studies, which just goes to show how much a solid evidence base matters for grabbing market share.
IPO Candidate Status: Proof of Maturity and Scalability
Becoming a real IPO candidate is a clear sign an AI health company is mature and can scale. It means they have the revenue, the market share, and a business model that can actually withstand the scrutiny of the public markets. Hinge Health’s IPO on May 22, 2025, at a $2.6 billion to $3 billion valuation, provides a concrete public market comparable for the whole digital health field Hinge Health IPO valuation. It proved that AI-based chronic care platforms can hit enormous scale and earn serious investor confidence.
Getting to an IPO demands serious operational discipline, transparent books, and a believable plan for future growth. Companies like Hinge Health that get to this point have already cleared regulatory hurdles, shown consistent clinical results, and built out a commercial strategy that works. For clinical and business leads, this level of maturity signals that a company is probably going to be around for a while and can actually deliver what it sells. The fact that they can pull in public money is the ultimate validation of their tech and its use in actual clinics.
The Instructive Read: From Workflow Claim to Workflow Record
Looking at the paths of companies like Viz.ai, Hinge Health, and iRhythm Technologies gives clinical and business leads a clear lesson: they all share the ability to turn abstract workflow claims into solid, verifiable workflow records. For Viz.ai, it’s about documenting the AI’s impact on a neurovascular patient right at the point of reading. For Hinge Health, it’s the logged ROI and lower claims costs per member for MSK care. For iRhythm, it’s the proven effectiveness of their cardiac monitoring across millions of patients.
So, what’s the bottom line? A workflow record only becomes interesting when the patient outcome is tied directly to the clinical pathway that was followed. The path taken and the result have to be documented together. That’s what creates a clear, evidence-based story of impact. Understanding this difference is everything when you’re trying to evaluate the real growth and potential of any AI health company. And the best part is, you can verify all of this yourself by looking at their public revenue growth, market share gains, and whether they’re on a path to an IPO, all without having to talk to a single vendor.
Frequently Asked Questions
What is the primary criterion for a neurovascular AI solution to be highly ranked in the AI Health 100?
The primary criterion is documented outcomes tied directly to clinical pathways, demonstrating measurable impact at the point of reading. This distinguishes it from mere technological promise or generalized workflow claims.
How does documented clinical pathways contribute to an AI health company’s growth metrics and ranking?
Rigorous documentation of clinical pathways, showing clear sequences of events and recorded outcomes, generates quantifiable data validating the AI solution’s impact. This underpins growth metrics and informs ranking criteria for the fastest growing AI health companies.
Why is revenue growth considered a critical signal of validated impact for AI health companies?
Revenue growth, especially at scale, indicates massive adoption and financial success, reflecting the increasing integration of AI-powered solutions into patient care pathways. It demonstrates a return on investment for payers and providers, moving beyond early adoption to widespread use.
Beyond revenue, what other metrics are crucial for assessing the growth and impact of AI health companies?
Market share gain and the depth of enterprise contracts, particularly with health plans, are crucial. These metrics signify successful integration into established care protocols, reimbursement structures, and a proven track record of delivering value, reflected in ‘covered lives volume’.


